Chapter 6 - The Freezing of the Golden Child
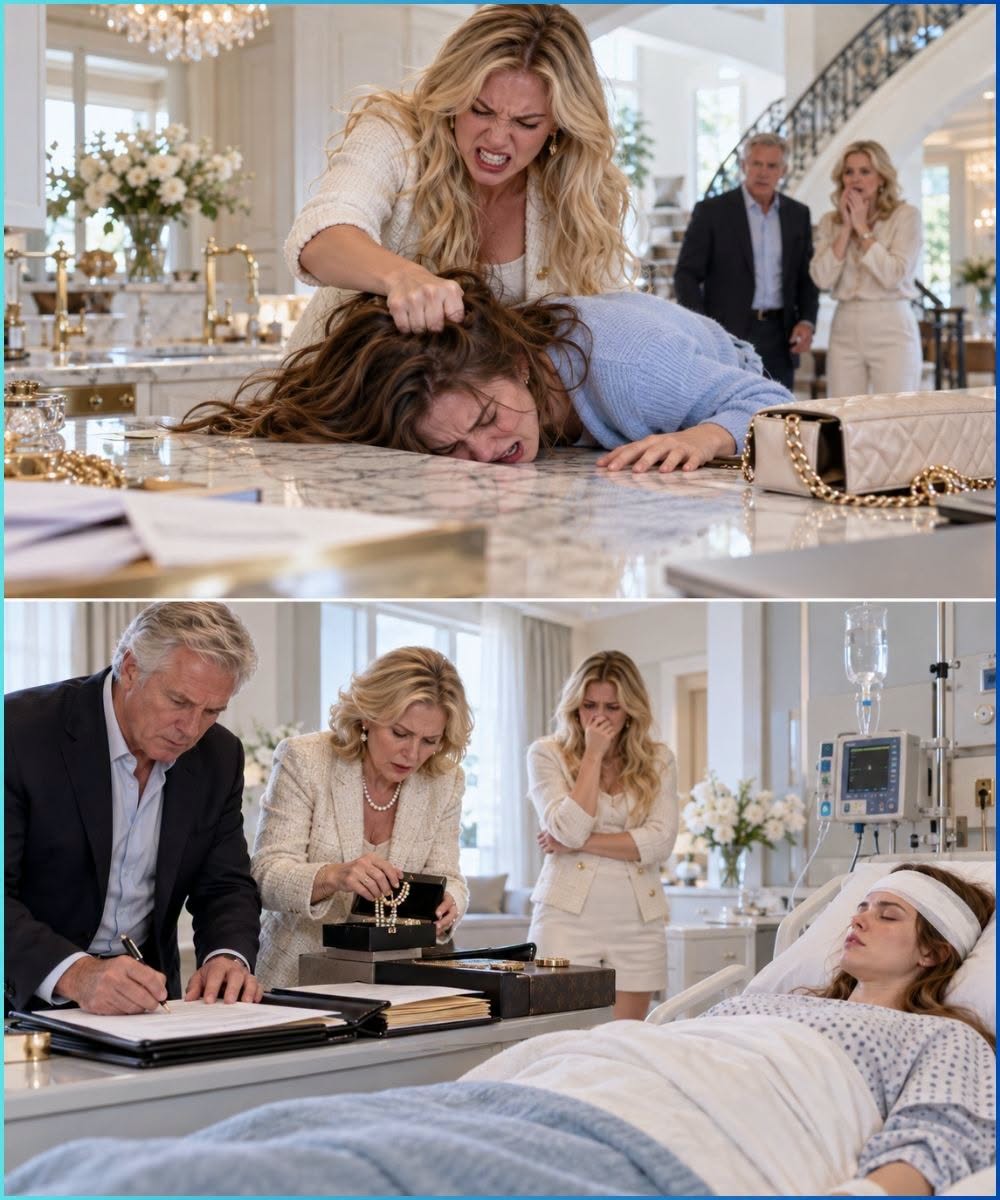
Over the next forty-eight hours, the fortress of lies my parents had built around Brooke didn't just crack—it imploded with catastrophic velocity.
Marcus Vance moved with surgical precision. Because of the clear evidence of identity theft and biometric tampering, Wells Fargo immediately reversed the twenty-seven-thousand-dollar wire transfers. The funds were restored to my checking account by Thursday afternoon.
Furthermore, Marcus contacted Grant Mercer, the private debt collector who had originally called me. Mercer wasn't an underground loan shark; he was a senior compliance investigator for a private mezzanine fund that specialized in commercial underwriting. When Marcus presented Mercer with the audio recording, the medical reports, and the proof that Brooke had forged my signatures on promissory notes using scanned copies of my tax returns, Mercer’s firm immediately severed ties with Brooke.
They didn't just close the account—they referred the case directly to the North Carolina Attorney General’s Financial Crimes Division.
By Friday morning, Brooke’s carefully curated fantasy world was crumbling on every front.
Her leased 2024 Mercedes-Benz C-Class? The leasing company was notified that the primary guarantor signature had been fraudulently executed. A tow truck pulled up to my parents’ driveway at 8:00 AM on Friday and repossessed the vehicle in full view of the entire neighborhood. Brooke had literally run out onto the lawn in her bathrobe, screaming at the repo driver while neighbors recorded the entire humiliating spectacle on their iPhones.
Her brand sponsorships? Marcus sent a formal cease-and-desist letter to the boutique cosmetic line and the luxury lifestyle brand that Brooke promoted, notifying their legal teams that their influencer partner was currently under active criminal investigation for felony assault and grand larceny. Within four hours, both brands terminated their contracts, scrubbed Brooke’s face from their marketing pages, and demanded refunds for prepaid promotional retainers.
Meanwhile, I was recovering at Marcus’s guest house in SouthPark, surrounded by quiet gardens and round-the-clock nursing care paid for out of an emergency victim-restitution escrow account Marcus had established.
My phone didn't stop buzzing for three days.
At first, it was rage.
Brooke (Thursday, 2:15 PM): You ruined my career! The cosmetic brand canceled my contract! They want ten thousand dollars back! You are an evil, jealous monster!
Then came the guilt trips from my mother.
Mom (Thursday, 6:40 PM): Avery, how could you do this to your family? Your father’s blood pressure is dangerously high. He had to see his cardiologist today. If he has a stroke, it will be entirely your fault. Drop these ridiculous charges immediately. We can handle this privately.
Then came the begging from my father.
Dad (Friday, 11:20 AM): Avery, please call me. The detectives came to the house this morning. They want to interview us about the cleaning supplies and the towel. Brooke is hysterical. She hasn't eaten in two days. We made a mistake, sweetheart. We panicked. But we are your parents. You can’t put your own sister in prison.
I didn't answer a single message.
For the first time in my life, I felt no guilt. The thick gauze over my stitches reminded me every second of what they were willing to sacrifice. If I had died on that kitchen floor, they would have rolled my body onto the patio pavers, cleaned up the blood, and told the coroner I was clumsy.
They didn't love me. They loved what they could extract from me.
On Friday evening, Marcus walked into the sunroom where I was sitting with a cup of chamomile tea, a thick legal binder tucked under his arm.
“Here’s the financial forensic report on your parents’ estate,” Marcus said, dropping the binder onto the mahogany coffee table.
I frowned, looking up at him. “My parents’ estate? What does that have to do with the criminal charges?”
Marcus smiled, and it was the coldest smile I had ever seen on an attorney.
“Avery, why do you think your parents were so desperate to protect Brooke from that fifty-thousand-dollar debt? Why didn't Martin just write a check from his home equity line or his retirement accounts to bail her out?”
“Because Dad is cheap,” I replied. “He always makes me pay for things.”
“No,” Marcus said, leaning in. “Because Martin and Elaine are completely broke.”
I froze. “What?”
“Their four-thousand-square-foot house in the country club development? It’s mortgaged to the hilt. Two second mortgages, three maxed-out home equity lines of credit. They took out over four hundred thousand dollars in debt over the past five years to fund Brooke’s luxury lifestyle—her trips to Paris, her designer wardrobes, her leased cars, her fake entrepreneurship.”
Marcus turned the binder to page twelve.
“And guess who owns the primary private mortgage on their house right now?”
I looked down at the documents. My eyes widened in total shock.
The private investment trust that held the first lien note on my parents’ four-thousand-square-foot home was a subsidiary of the commercial real estate syndication fund where I served as the senior underwriting appraiser.
In fact, six months ago, I had personally signed off on the portfolio acquisition of those bundled residential notes without realizing my parents’ property was buried inside the sub-tier schedule.
May you like
“Marcus,” I breathed, looking up at him as the pieces fell into place. “They haven't made a mortgage payment in four months.”
“Correct,” Marcus whispered. “The note is in technical default. As of Monday morning, the trust has the legal authority to initiate immediate foreclosure proceedings. And as the authorized regional portfolio manager with full power of attorney for the fund, you hold the pen that decides whether they get an extension... or whether they get thrown out on the street.”